
Funding a holiday home
Date
09 November 2017
Share

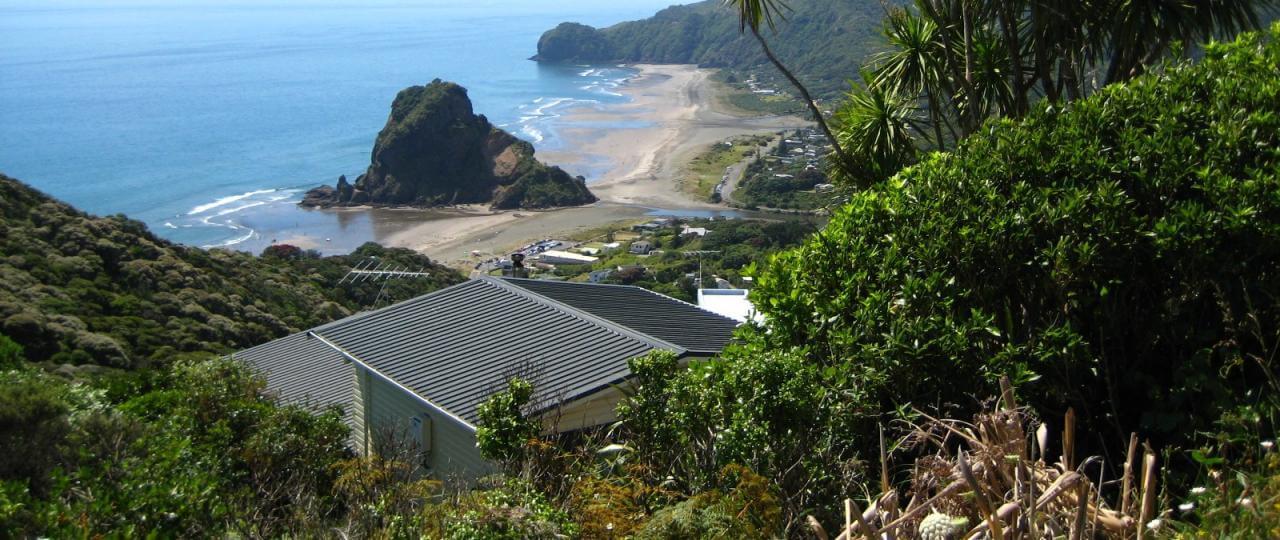
With summer just around the corner, you may be thinking about buying your own holiday home; whether it’s the quintessential kiwi bach on the beach or a second home by the lake, the idea is a pleasant one. But when it comes to purchasing, will a lender consider it an investment? And can rental income be taken into account when borrowing to fund a holiday property? And what about RBNZ rules around LVR (Loan to Value Ratio)?
If you do rent the property to others when you’re not using it, standard mainstream bank investment property rules apply, which means you can borrow up to 60 percent of the value of the property or up to 65 percent of the value of the property from January 2018.
If you’re wanting to use rental income to service the loan against the property, the lender is likely to consider the average of the income it generated in the last two years. It’s worth noting, that to allow for holding costs – that’s the rates, maintenance expenses, insurance and so on – the property income will be sensitised back to something like 75 percent.
If you don’t rent the property out, it is deemed a second residence, and consequently the RBNZ rule would typically allow up to 80 percent of the sale and purchase agreement or registered valuation.
At Finance New Zealand, we work with all the major banks as well as specialist property funders. When lending falls outside the standard LVR ratios, our non-bank financiers have greater flexibility to lend than the mainstream banks. If you would like to discuss funding a holiday property, or apply for pre-approval, give us a call.
Similar Posts
25 August 2026
Funding a Business Purchase or Shareholder Buyout
Buying a business, buying into an existing business or funding the exit of a shareholder can be a major step — and finding the right funding structure can be more complex than a standard finance application. At Finance New Zealand, we look at the whole transaction and the wider business, rather than simply looking for one loan to cover the purchase price.

12 August 2026
What IPP3A Means for Finance New Zealand Clients
From 1 May 2026, a new privacy requirement known as Information Privacy Principle 3A (IPP3A) came into effect under New Zealand’s Privacy Act. The change is designed to give you greater visibility over where your personal information comes from and how it is being used. For Finance New Zealand clients, the way we help you arrange finance isn’t fundamentally changing. What you may notice is some additional privacy information or notifications when you apply for new lending or make changes to your existing finance.

Page Links
Contact us
Finance New Zealand Limited L11 BDO Tower, 19-21 Como Street, Takapuna, Auckland 0622 PO Box 65164, Mairangi Bay 0754 T: (09) 222 0320E: info@financenz.co.nzStay connected
Member of
Proud Sponsors of Auckland Rescue Helicopter Trust
Copyright Finance New Zealand Ltd 2026