
Funding for property development
Date
16 October 2018
Share

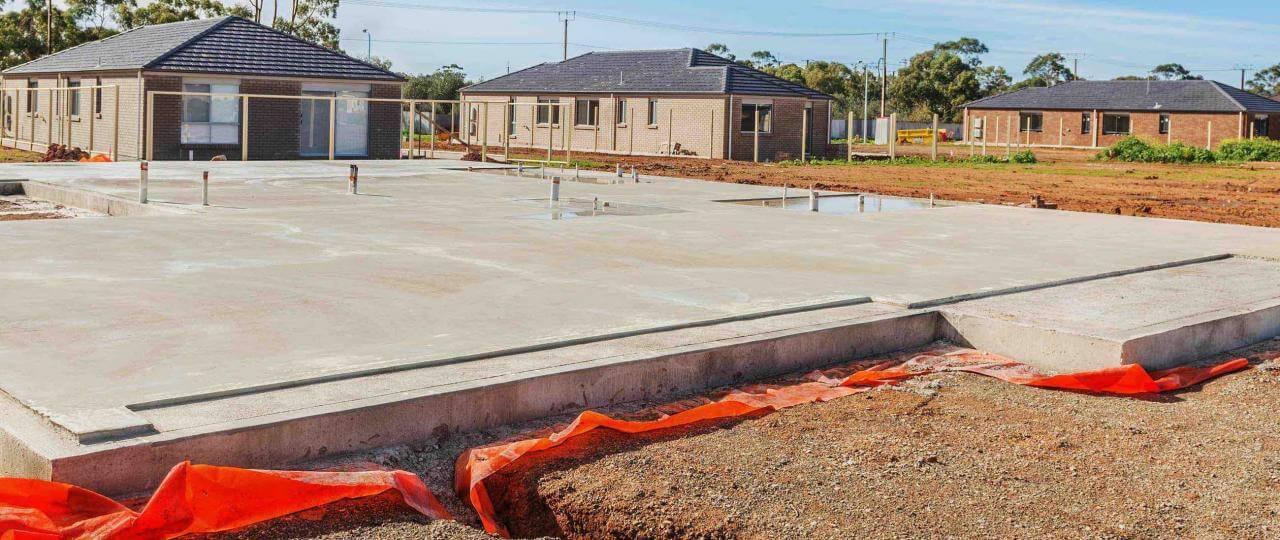
Property development remains a hot topic of conversation. After swinging from being the darling of the banking world to something they were reluctant to touch, funding for property development is back on the radar of the main banks.
Affordability is a big concern – large deposits are required, and rising property costs mean bigger mortgages are needed, which means there are fewer buyers in the property market. Also, consumer demand is increasingly for the finished product. This makes it harder for developers to sell off the plans, which in turn makes it harder for them to source the funds they need to complete their projects.
Location is a factor too. There are worries around oversupply in areas like Christchurch. In contrast, a shortage of supply in Auckland, Queenstown and the central Otago region, Tauranga, and Hamilton means lenders look more favourably on property development projects in these regions.
Many of the transactions that Finance New Zealand have facilitated have been through specialist property funders. This is largely because specialist property funders usually only require a valuation before drawdown, while banks will often request valuations and QS reports, to name a few.
And while the main banks are looking after their existing customers well, any new lending would require the property development to be “bullet proof”, with lots of presales secured before the banks will take on the deal.
Specialist property funders do garner higher rates than the main banks, but in the long run, they can actually be cheaper as the loan conditions are fewer, and the ease of obtaining funds will ensure your project keeps moving.
If you need funds for property development, talk to your business partner at Finance New Zealand. We can work with you to assess the options for, and relative pros and cons, of main bank versus non-bank property development finance.
Similar Posts
25 August 2026
Funding a Business Purchase or Shareholder Buyout
Buying a business, buying into an existing business or funding the exit of a shareholder can be a major step — and finding the right funding structure can be more complex than a standard finance application. At Finance New Zealand, we look at the whole transaction and the wider business, rather than simply looking for one loan to cover the purchase price.

12 August 2026
What IPP3A Means for Finance New Zealand Clients
From 1 May 2026, a new privacy requirement known as Information Privacy Principle 3A (IPP3A) came into effect under New Zealand’s Privacy Act. The change is designed to give you greater visibility over where your personal information comes from and how it is being used. For Finance New Zealand clients, the way we help you arrange finance isn’t fundamentally changing. What you may notice is some additional privacy information or notifications when you apply for new lending or make changes to your existing finance.

Page Links
Contact us
Finance New Zealand Limited L11 BDO Tower, 19-21 Como Street, Takapuna, Auckland 0622 PO Box 65164, Mairangi Bay 0754 T: (09) 222 0320E: info@financenz.co.nzStay connected
Member of
Proud Sponsors of Auckland Rescue Helicopter Trust
Copyright Finance New Zealand Ltd 2026